Saturday, July 30, 2022

Are We Worrying About the ‘Right’ Retirement Risks?

As if there wasn’t enough to worry about regarding retirement—a new research paper suggests we’re not worrying about the “right” things.

More precisely, that paper, published by the Center for Retirement Research at Boston College, was titled, “How Well Do Retirees Assess the Risks They Face in Retirement?” And, as you might suppose, the answer provided at the conclusion of the paper is—“not very well.” 

The premise of the paper relies on the author’s identification of five major risks in retirement, which turn out to be:

  • Longevity risk (the risk of outliving one’s resources)
  • Market risk (the financial risk not only from the markets, but from things like the housing market)
  • Health risk (the risk of unexpected medical and long-term care expenses)
  • Family risk (the risks arising from divorce, death, or the unexpected illness of an adult child)
  • Policy risk (notably the sustainability at current benefit levels of Social Security)

Arguably, all of these are legitimate risks that need to be considered and dealt with as part of any reasonable retirement plan, though one might argue that even these aren’t exhaustive (consider, for example, inflation—but more on that in a moment).

The paper’s author performs some statistical alchemy and then determines that the three top risks retirees should be worrying about are:

(1) longevity; (2) health; and (3) market.

But, according to the author’s analysis retirees are most worried about are:

(1) market; (2) longevity; and (3) health.

Now, despite the headlines[i] that followed the publication—and aside from the specific ordering—those actually seem to match up pretty well to me. However, the “point” seems to be that retirees are more worried about the market than they “should” be, that the bigger risks to their retirement are that they might outlive their savings—and/or that their bad health might drain them faster than expected—but they’re focused on the market impact on savings. Bottom line: retirees are worried about the “wrong” things.

At this point, a couple of points should be made. First, the assessment of what these retirees are worried about was drawn from 2016 data. And secondly, the conclusions about what retirees are concerned about are gleaned from a series of questions in that databank[ii]—which, with the “help” of the author’s calculations, are turned into those weighted sentiments of concern. And then, having crafted some subjective sense of the relative concerns of those elements, the author purports to establish the “objective” benchmark against which they are to be judged. 

Market risk falls relatively low on this scale because of his assumed 20-year investment horizon in retirement, though retirees may lack that confidence, particularly these days.

The paper’s author concludes by highlighting the need to educate the public on these various retirement risks (and presumably their relative importance, based on their likely impact), most specifically the need for lifetime income products (to shield against the longevity risk) and long-term care support (to buffer against the health care concerns).

Now, I’d argue that a judgment based on subjective 2016 data doesn’t tell us much about what retirees (particularly these days) are actually concerned about—and even if it did, it doesn’t seem to me that there’s enough difference in priorities to matter. 

To me, it’s not so much which risks retirees are concerned about, much less their ordering—but that they are aware of the potential risks and seeking help on how best to mitigate them. But what I do think is important—and here I agree with the study’s author—is (more) education about the multiple potential risks to retirement security—and not just for those already in retirement, but for those of us still trying to make preparations against those risks. 

- Nevin E. Adams, JD


[ii] The source data—the Health and Retirement Study (HRS)—asks respondents to assess the probability of various outcomes. The respondents give a number from 0 to 100, where 0 means absolutely no chance and 100 means absolutely sure to happen. And for these purposes, the questions ranged from “the probability that stocks will be worth more next year than they are today,” to the chance of gaining 20% or more over the next year and the chance of losing 20% or more, to the probability of the probability of spending $1,500 or more in the coming year on health care.

Saturday, July 23, 2022

The Sure Not-So-Sure Thing

 By some accounts, I just spent the past week in “retirement”—driving around sightseeing, reading some good books, hanging out with family, and yes—even walking on a beach.

And I have to tell you—if that was retirement, I don’t know how I’m going to afford it.

Now, I realize that isn’t the stuff of most “real” retirements, though it is frequently the stuff of retirement planning brochures. My week was a family vacation, and it was spent doing the things that families do on vacations.[i] And it served as a stark reminder that while sitting on a beach doesn’t cost much, making arrangements to stay—and eat—in proximity to the aforementioned beach is a whole other financial consideration.

That said, when those actually in retirement are asked about their retirement confidence—well, it’s pretty high. According to the Employee Benefit Research Institute/Greenwald Associates annual Retirement Confidence Survey, 77% of current retirees report feeling either very (33%) or somewhat confident about having enough money to live comfortably throughout their retirement years. All of which suggests that if there’s a lot of uncertainty about what retirement will be like/cost, once you’re “in it”—well, you both have a sense of what it’s going to cost, and how much you have to cover it.[ii] That, by the way, despite the reality that the same RCS has for years found that significant numbers of individuals have found themselves in retirement through no choice of their own[iii]—sometimes due to health, sometimes due to employment-related decisions. 

Today we are looking at an unusual confluence of events: a tight job market in the middle of what has been termed the “Great Resignation,” surging inflation at rates not seen in a generation, and investment markets that, after a remarkable run-up—well, let’s just say it’s been rough on most 401(k) accounts. We’re getting the same kinds of investment advice we always do/give during such downturns—but one can’t help but wonder if it’s “different” this time—if the disruptions are anything but “transitory.”

“Disruptions” are the bane of a fixed income, of course. Just when you think you have it all balanced out, you have to spend (a lot) more for gasoline, pay a higher real estate tax bill, scrape up some money for a new prescription drug, or deal with the financial consequences of an unexpected medical emergency (or that of a loved one). That this happens at the same time that your investment portfolio is taking a sustained “hit” contributes to the sense of economic pessimism that garners so much press, polling and political aspirant attention in this election season. Without question, things cost more than they did (when you can find them on the store shelf), and those on fixed incomes (and that includes a growing number of current workers who perhaps haven’t gotten a pay increase in a while) have to make “adjustments”—often painful ones. And if all of this doesn’t warrant changes in financial plans, it certainly warrants a new level of discussion about them.  

Perhaps the only “sure” things are death and taxes after all—but the lesson for those of us still drawing a paycheck and planning for retirement is the importance of preparing for that third “sure” thing when it comes to retirement planning: uncertainty.

- Nevin E. Adams, JD


[i] In fairness, we also spend a day tracking down the gravesites of some ancestors, and that probably isn’t on most vacation agendas!

[ii] It’s worth highlighting, of course, that workers reporting they or their spouse have money in a DC plan or IRA or have benefits in a DB plan from a current or previous employer are twice as likely as those without any of these plans to be at least somewhat confident (83% with a plan vs. 40% without one). 

[iii] In the 2022 RCS, 32% who retired earlier than planned say they did so because of a hardship, such as a health problem or disability, not related to COVID-19. Another 23% say that they retired due to changes at their company, but 38% say they could afford to retire earlier.

Saturday, July 16, 2022

Back to ‘Normal’?

Things are—slowly—getting back to normal. Planes are filling up, commutes are slowing with increased traffic volumes, and in-person meetings are back underway. 

And while for many readers things have been back to “normal” for some time, I’ve had the opportunity over the past two months to participate in three separate advisor events that were the first such in-person gatherings since the onset of the pandemic.

We’ve learned not only how to navigate things like virtual committee meetings and education sessions, but found that in many cases those platforms could be even more effective in extending our reach to individuals who might not have made it to an in-person session, or who might have been more receptive to those messages in the wake of COVID concerns about health and job security. 

While we’re not quite “done” with COVID (and perhaps we never will be), we’ve learned a lot of valuable lessons. The notion that we have to be in a physical office to be productive has been soundly rebuffed. At the same time, in every in-person gathering I have had the opportunity to be part of these past several months, there is an energy, an excitement, an enthusiasm that transcends any I’ve experienced in even the most engaging “virtual” formats. Oh, one day in the distant future we may not need that social connection—or perhaps we’ll simply tell ourselves that whatever is “lost” is more than compensated for by the convenience and cost savings of remote engagement.

But “those” days aren’t yet these days—and in just a couple of weeks we’ll be convening—in person—for our 10th annual NAPA D.C. Fly-In Forum. I still remember attending the first one as a “special guest,” and being struck even then by the quality of the program and speakers. More importantly, the room was full then—as it continues to be—of the nation’s leading retirement plan advisors, networking and engaging not only with each other, but with some of the most influential voices in Washington.

This year looks to be no exception—and as impactful as last year’s “virtual” version surely was, it really can’t compete with the reality of an in-person event—not to mention the opportunity to walk to—and through—our nation’s Capitol. 

We’ll have a lot to talk about—while the Labor Department’s next steps on the so-called fiduciary rule and ESG rules have just been pushed back, the final proscriptions of PTE 2020-02 have just taken hold (notably the requirement to document, in writing, the best interest case for a rollover recommendation), and the controversy regarding the recent compliance assistance release on cryptocurrency is still reverberating. 

This year’s Fly-In Forum will feature comments from Ali Khawar, who has been serving as Acting Assistant Secretary for the EBSA, as well as Zeena Abdul-Rahman, Branch Chief, Investment Company Rulemaking Office, Division of Investment Management at U.S. Securities and Exchange Commission to speak to ESG, as well as a very special panel of Hill staffers for some “inside the Beltway” perspective, and a panel of expert ERISA litigators to discuss recent developments, and provide insights on staying out of court. And no NAPA D.C. Fly-in Forum would be complete without the appearance of key legislators, which this year will include Sens. Ben Cardin (D-MD), John Barrasso (R-WY) and Rob Portman (R-OH) to shed light on the incredible opportunities contained in SECURE 2.0, RISE & SHINE, the EARN Act, and/or the combination/assimilation of all of the foregoing.   

But for me—and for the dozens of advisors who have participated over the past 10 years—the most impressive aspect of our Fly-In Forum is the second day, where delegate-advisors have an opportunity, assisted (and prepped) by the NAPA GAC team, to meet with legislators and their staff on Capitol Hill, to share your perspectives, ideas and concerns, based on your front-line, real-life experiences working with retirement plans, plan sponsors and participants. Heading into a crucial mid-term election cycle, your voice—your insights and perspectives—have never been more critical.

Whether you’ve done this a dozen times, or have never had the opportunity, the NAPA D.C. Fly-In Forum is an amazing “first-hand” experience. For those ready to get off the sidelines and contribute to a real difference in retirement policy, you won’t find a better “ticket” than the NAPA D.C. Fly-In Forum.

Things may be getting back to “normal”—but it’s anything but business as usual.

- Nevin E. Adams, JD

Saturday, July 09, 2022

Looking Before You 'Leap'

As new rules about rollover disclosures kick in, a new report highlights an often unacknowledged risk of rollovers—high(er) fees.

That’s right—a new report from Pew Trusts seems to have stirred up a new awareness of that issue—all this attention just as PTE 2020-02 brings the written requirement of why a rollover is in the best interests of participants into play.

That difference shouldn’t come as a surprise to anyone who has ever compared the fees in their 401(k) to an IRA. Most 401(k)s benefit from institutional pricing, and if the menu of available investment options isn’t quite as broad as that in an IRA, they benefit from the selection and monitoring by ERISA fiduciaries. Yes, IRAs are just that—individual retirement accounts—smaller, generally speaking with more options—and yes, much more likely to be charged retail mutual fund fees—more expensive. In that sense the report—though it’s garnered headlines of late—doesn’t really tell us anything we didn’t know, if we’d only stop to acknowledge it. 

However, sure as I am willing to accept the conclusions based on both personal experience and professional acumen, I am a tad skeptical in the results of the analysis. The title is truer than one might expect. The title of the report speaks volumes as it says: “Small Differences in Mutual Fund Fees Can Cut Billions From Americans' Retirement Savings.” Because, after all, it surely could—but does it?

The report that is garnering so much attention now claims that, in the aggregate, the amount of retirement savings lost in such rollovers potentially reaches tens of billions of dollars. Citing data from the Investment Company Institute, the report notes that in 2018 alone, investors rolled $516.7 billion from employer retirement plans into traditional IRAs. They go on to assert that an analysis of fee differentials suggests that over a hypothetical retirement period of 25 years, those retail investors could see an aggregate reduction in savings of about $45.5 billion—just from that single year of rollovers.

Math ‘Problems’

The analysis—based on data from Survivor-Bias-Free U.S. Mutual Fund Database, Center for Research in Security Prices—though it relies on medians and averages for its fee conclusions—and, based on those, it asserts that annual expenses for median retail shares (ostensibly what you’d have access to in an IRA) were 0.34 percentage points higher than those for institutional shares (again, ostensibly what you’d have access to via your typical 401(k). Similar projections are presented for hybrid, and for what the analysis purports to be the smallest median fee difference. Having chosen these points of reference, the analysis simply does the math.[i]

Rollover Rationales

Regardless of the size of the differential—what role, if any, do fees play in these rollover decisions? Suffice it to say—not much. 

At least according to another report[ii] published last September by Pew, based on a survey of 1,125 older workers and recent retirees ages 55 to 75 between May 12 and June 5, 2020—roughly half currently and the rest working full time, though all had at least $30,000 in retirement savings. The survey asked participants a series of questions about whom they had consulted in deciding what to do with their retirement savings and how they planned to handle their savings (in the case of those still working), or what they had done with their savings (in the case of retirees).

Now, there are many reasons underlying the distribution decision—fees, convenience, investment options—but when the workers weighed in they said they were most motivated to stay in their current plan because they preferred the investment options—a reason cited by 50% of respondents as the most important reason, and mentioned by nearly three-quarters (73%) as at least one reason why they intend to leave their savings in their current plan when they retire. Not surprisingly—since those surveyed had at least $30,000 in savings—more than half felt that staying in their current plan would be convenient.

On the other hand, only about 3 in 10 were motivated to plan on keeping their savings in their current plan because they thought it would have lower fees than other options, and a mere 15% said lower fees in their current plan was the most important reason for planning to leave their savings where they are.

‘Control’ Voice

Near-retirees planning to roll their savings into an IRA at retirement were similarly motivated by convenience and investment options, according to the report. However, the strongest motivating factor for those respondents was the ability to have greater control over their investments, with more than 6 in 10 (63%) saying that was one reason that they planned to roll their workplace savings into an IRA, while for nearly 4 in 10 it was the most important reason. Roughly a quarter said that investment performance was behind their plan to move their savings into an IRA when they retired, and the same number actually said it was because the IRA had lower fees. 

Control was most important among retirees as well; about 18% of retirees cited lower fees as a reason for rolling over their savings, slightly less than the 25% of near retirees who cited fees as a reason—more specifically that the IRA had lower fees than their current plan. Only 4% of retirees said it was the most important reason, nearly identical to the 3% of near retirees who said the same.

Said another way, fees were not a major consideration in the rollover decision—and when it did manifest itself as a reason, it was because the IRA fees were believed to be lower than their current plan. Which, again, in view of certain market realities, suggests that those workers didn’t appreciate/understand the fees paid in their 401(k).  

The reality is, a small difference in mutual fund fees can cut billions from Americans’ savings—an impact that, unfortunately, many of those contemplating a rollover may not realize[iii] or prioritize in their decisions. 

That said, while those new disclosures documenting why a rollover is in the participants’ best interest may not solve the problem—they should make it easier for advisors to help them better understand what they may be giving up. And perhaps all of this attention to this important issue will help participants who aren't working with an advisor to "look" before they simply leap... 

- Nevin E. Adams, JD

[i] While the comparisons are certainly “directionally” accurate assuming the math is correct, the size and scope of the impact surely suffer from the imprecision of the markers employed. But considering the sheer size of the rollover market (it now outpaces that of the 401(k), it’s surely a significant amount.

[ii] Pew Survey Explores Consumer Trend to Roll Over Workplace Savings Into IRA Plans

[iii] The Pew report notes that “although few said that they would continue a rollover into an IRA with higher fees than their workplace plan, previous research by Pew has shown that many people struggle to fully understand their investment fees. Just 25% of workers in an earlier Pew survey said that they had read and understood the fee disclosure of their retirement account. 

Saturday, July 02, 2022

Dividing Lines

 It’s been said that there remains more that unites us than divides us—but that’s not how it feels most days. 

However, such times are not all that unusual for this diverse nation. Indeed, if today’s battle lines do seem harsher and more extreme, my sense is that it’s only because they are magnified by media and social media, transported to us every minute of the day and night by devices we dare not relinquish any longer than to recharge the battery.

Consider the nation’s declaration of independence which we will commemorate on Monday. Students of history—not to mention aficionados of the musical 1776 or readers of David McCullough’s John Adams or viewers of its HBO miniseries adaptation—know that the decision to declare independence was no easy matter. Indeed, the political bartering and frustrations involved in getting to a “unanimous Declaration of the thirteen United States of America” would have been all-too familiar to the legislators of today. Even then, it was declared to be “unanimous” only because one of the 13 colonies voting was persuaded to abstain from the vote rather than oppose it. 

While we celebrate the Fourth of July as Independence Day, that is neither the day on which the Continental Congress passed the resolution (July 2), nor the day on which the declaration was signed by the members of that Congress (only President of Congress John Hancock and Charles Thomson, Secretary, signed it on the 4th (the former in a hand “large enough for King George to read without his spectacles”). Most delegates didn't sign it until August 2. One didn't sign until 1781. Three delegates never signed.

The signers—who stood to lose everything they possessed, including their lives—surely did so with trepidation. Indeed, Hancock reportedly said at the signing (on August 2) that they must all stick together—to which Benjamin Franklin reportedly responded, “Yes, we must, indeed, all hang together, or most assuredly we shall all hang separately.” 

Of course, that declaration was neither the beginning nor the end. Hostilities with England had already been underway for more than a year, the terrible winter at Valley Forge was more than a year in the future, General Cornwallis’ surrender at Yorktown was still more than five years off, and an official end to the hostilities would not come until 1783. 

Invoking the Vision

Less than 100 years later, even as the nation approached another Independence Day celebration, President Abraham Lincoln would find himself in the middle of an enormously unpopular war fought to keep the nation together, while two American armies converged at Gettysburg for what would be the bloodiest battle in the nation’s history. Even so, President Lincoln later that year invoked the vision of the nation’s founders to launch his Gettysburg Address with the words; “Four score and seven years ago our fathers brought forth on this continent, a new nation, conceived in liberty, and dedicated to the proposition that all men are created equal.” This at a time when the outcome of that conflict—and his own reelection prospects a year later—were anything but certain. 

Without question we live in times of great social distress, where it seems that everything, literally everything, has been polarized and politicized into divergent and irreconcilable camps. Those looking for common ground or points of potential agreement seem to be few and far between, while those seeking compromise are typically condemned for trying. Indeed, the choices our nation faces today—on terrorism, the fighting in Ukraine, health care, energy costs, inflation, the economy, and yes, even retirement savings[i]—seem relatively modest in scope when considered next to the daunting prospects our forefathers faced in 1776. What they could not have had at that time—but what their vision has surely bequeathed to us—is a confidence in what we now consider American ideals and the resilience of the American spirit.

Their sacrifices were made a long time ago—and the liberties they fought to win, and later to preserve, are so interwoven into the fabric of our day-to-day expectations that it is easy to forget just how precious and rare they remain in this world. 

With all its faults, all its frailties, what we have here remains a special gift. It’s a national treasure we should appreciate every day—even if we only celebrate it once a year. 

- Nevin E. Adams, JD


[i] Those of us who have committed ourselves to build, expand and nurture a more secure retirement for American workers have to find solace in the overwhelmingly bipartisan legislative efforts—both in recent months, and before—in support of that goal. 

Saturday, June 25, 2022

Path(s) of Least Resistance

So, how many 401(k) accounts do you have?

At the moment, I have four—one from each of the employers in my career (including this one), all except the first one (that one went for law school and a house downpayment). Apparently I’m not alone. A recent survey of Plan Sponsor Council of America members found that only 18% of respondents had a single 401(k) account. Nearly as many (14.3%) had five. As it turns out, three was the most common response.

I joke that it’s just “market research”—after all, what better way to assess the quality of various retirement plan offerings than to have your own 401(k) supported by some of the best? Sure, there’s been institutional pricing at one that I’d hate to lose, access to a specific managed account platform that I value, and a really cool online platform at another—and then, in the back of my mind, is a concern that the taxability detail might get “jostled” in the process—in short, plenty of reasons to rationalize my leaving them where they are. But the truth of the matter is that moving your account remains a bit of a pain.

That has a number of implications, not the least of which is people can (and do) lose track of those “left behind” 401(k) accounts. That’s been an issue of some concern by both regulators and legislators alike—with potential remedies (or at least remedial efforts) like a “lost and found” directory. Perhaps just as significantly, the SECURE Act’s directive with regard to reporting projected retirement income numbers on participant statements won’t do anyone much good if it’s based on only one of the three or four account balances you actually have.[i]

There are other dangers[ii] in having multiple accounts—as they create multiple opportunities for hackers to access them. This is a particular concern when there’s been a change in recordkeepers (which is happening a lot these days), when you have a new account set up for you—but you don’t get around to promptly establishing a secure password (along with multi-factor authentication, personalized answers to key security questions, and electronic notifications of any changes to your account). After all, if you don’t lay claim to that account—quickly—it’s all the easier for a hacker to do so.  

Now, I’m guessing that the reality is that most people who leave their 401(k) accounts behind do so simply because it has become the easy no-action-required default (well, as long as your balance is over $5,000—if less than that, and certainly if less than $1,000, your “easy” default is likely a lump sum payment, taxed, and likely subject to premature withdrawal penalties as well. Indeed, the leakage that so many fret over—due to hardship withdrawals or loans—is fairly inconsequential. The exception, of course, is the loans that are outstanding when termination occurs—as well as the “forced” distributions at termination. A recent assessment by Alight notes that 80% of people who had an account of less than $1,000 cashed out at termination, while nearly two-thirds of those with balances between $1,000 and $5,000 did so.

Enter the Advancing Auto Portability Act of 2022, introduced by Sens. Tim Scott (R-SC) and Sherrod Brown (D-OH), provisions of which have been incorporated in the recently introduced Enhancing Americans’ Retirement Now (EARN) Act. The size of the leakage issue the legislation seeks to stem has been wildly exaggerated by some, but the Employee Benefit Research Institute credibly says auto-portability has the potential to preserve up to $1.5 trillion in retirement savings over a 40-year period. 

That’s right—just like automatic enrollment helps people get started doing the right thing, auto-portability is basically an infrastructure design that automatically helps participants—and most notably participants with small balances—and rolls those balances into an IRA, and then—if available and desirable—rolls that into their new employer’s retirement plan. But more than giving it structure, and legislative “legitimacy” (the Department of Labor lent some help in terms of a prohibited transaction exemption in 2019), the legislation provides a $500 tax credit for adopting small business employers to defray the costs of making the connections.     

Now, at the point of my job changes, it wouldn’t have taken much for me to decide to roll those balances into my new employer’s plan—but it took absolutely nothing at all for me to just leave them where they were—the path of least resistance. On the other hand, the default for those who have smaller balances—who are often just getting started doing the right thing by saving—is a default that requires that they “start over”—with a “forced” distribution, and one reduced by state and federal taxes, and likely a 10% penalty to boot. 

It's time we all had a path of least resistance that makes it easy for us to do the “right” thing. And now perhaps we do.

- Nevin E. Adams, JD


[i] In fairness, there are already concerns that the calculation proposed by the Labor Department in response to the SECURE Act’s directive already has shortcomings. Specifically, it would assume that the participant: (1) is retiring at age 67 (the Social Security full retirement age for many workers) or the participant's actual age, if older than 67); (2) uses an interest rate that is the 10-year constant maturity Treasuries (CMT) securities yield rate for the first business day of the last month of the period to which the benefit statement relates; (3) estimates life expectancy from a gender-neutral mortality table pursuant to IRC Sec. 417(e)(3)(B)—oh, and the biggie—(4) uses the current account value—assuming no further contributions.

[ii] Another “casualty” of multiple 401(k) accounts? When a provider publishes a list of “average” 401(k) balances (and 401(k) critics pounce on those as inadequate)—well, they might not have the whole picture. 


Saturday, June 18, 2022

Conversation "Starters"

 This weekend is, of course, Father’s Day—but my dad’s decision to retire was driven more by time than timing. 

Like many of his generation, once he got to 65, it was time to “retire.” He didn’t have a pension (fortunately for him, my mother did), though he had Social Security, and savings in a 403(b) plan that he contributed to later in life—reluctantly—once he saw Mom’s modest savings in her 403(b) account grow.  

My dad was a man of (very) few words—at least spoken words. Conversations with him generally required… effort. Oh, he’d respond to direct questions, but his answers tended to be short and—well, direct. Again, like many of his generation, mostly he was content to let my mother be the conversationalist in family settings.   

So, when Dad turned to me one weekend afternoon for some input on his retirement planning—well, I was surprised. Not that it didn’t warrant a discussion, mind you—but it was not something we had ever discussed—and more’s the pity. That said, I dived into the financials, played through some spreadsheet projections, and—at the end of what I hoped was an educational and enlightening discussion of his options and trade-offs, their upsides and potential downsides—when I was sure that I had been able to unwind and demystify the maze and presented him with a straightforward presentation of alternatives, there was this long pause—and then, he turned to me and, as politely as he could, said, “I just want to know how much money I’ll have to live on every month.”


That, of course, was also the mindset of many in my dad’s generation—not how much we’ll need, but how much we’ll actually have. Ultimately, of course—certainly at the brink of retirement, that’s the reality of living in retirement. 

Now, the 32nd annual Retirement Confidence Survey, published by the Employee Benefit Research Institute (EBRI) and Greenwald Research, finds that nearly three quarters (73%) of American workers feel confident in their ability to live comfortably in retirement—indeed, 28% feel very confident (though nearly 6 in 10 say that preparing for retirement makes them feel stressed). While that assessment predated the recent market tumult (and there has been some correlation between the markets and retirement confidence over the years), much less the sustained inflation “bite,”[i] Americans’ confidence in retirement has proven to be pretty resilient—and this despite the persistent finding that many haven’t taken the time to do even a single estimate of their projected needs[ii]—and, at least traditionally, that included measures as unscientific as “guessing.”

Now, as it turned out, my analysis of my dad’s situation (stripped of all the fancy “upside potential” possibilities) affirmed his retirement decision—or at least it didn’t put him off it. I’ve wondered from time to time since what he would have done if it hadn’t. My guess is that, like many Americans confronted with those same realities, he’d have “adjusted.” To this day, I feel really lucky that he didn’t have to (if mostly because my mom’s planning compensated for his lack thereof). 

If it’s a conversation you haven’t (yet) had with your parents—or kids—perhaps it’s time you did.

- Nevin E. Adams, JD


[i] Though, a third of workers and half of retirees who feel less confident cite inflation and the cost of living as the reason for their declining retirement confidence. 

[ii] However, and while it’s far from optimal, the most recent RCS did find that more than half (58 percent) ages 55 or older have tried to calculate how much money they will need to have saved so that they can live comfortably in retirement.

Saturday, June 11, 2022

Social Insecurities

Last week the Treasury Department’s Social Security Board of Trustees released its annual report in a classic case of good news, bad news.

The good news, of a sort, was that the date through which Social Security will be able to pay scheduled benefits was projected to be 2034—and while that’s not very far away, it was a year later than the prior year’s report had indicated. The bad news, of course, is that without some kind of adjustment the program won’t be able to pay those scheduled benefits beyond 2034.[i]

Now, that’s not the same as “going broke” or running out of money—but, as things stand now—assuming no adjustment is made—a possible outcome would be that the scheduled benefits paid would only be about three-fourths of “scheduled.”[ii]

What’s weird is that it’s hard to find anybody who seems to think the problem won’t get fixed at some point—though the definitions of “fixed” vary—and nobody is willing to hazard a guess on who’s going to step up, much less when or how. 

The ‘How’

Of course, the how is relatively straightforward. Years back, when the future crisis was no less real, but somewhat less large, I had the opportunity to hear former Federal Reserve Chairman Alan Greenspan speak on the subject of “fixing” Social Security. Greenspan, who had led a commission in the early 1980s charged with solving what was then a much more immediate crisis of the program (believe it or not), outlined the two core elements of any serious attempt to resolve the funding shortfall:

  1. increasing funding (generally either by raising the withholding rates or the compensation level to which they are applied, or both); and
  2. reducing benefits, either by raising the claiming age —or what’s euphemistically referred to as “means testing,” which effectively reduces the benefits to higher income recipients. 

So, the answer to the problem is, as the actuaries remind us, “just math,” and we needn’t choose one solution or the other; rather, some combination—as it was in 1983—is the approach that seems the most likely outcome. That said, if there’s any aspect of this that is as widely known as the fact that there is a looming financial shortfall, it’s that the longer we put off taking steps to do so, the more difficult—the more expensive—it will be.

Whatever that system’s historic successes, and the dependence of the nation’s retirees on its benefits, I think most in my generation—and certainly those in my children’s—have doubts as to its long-term financial sustainability. Adjustments have been made over time to address those potential shortfalls—the retirement age has been lifted, the taxes withheld from current pay to fund that system have been increased, the benefits paid from that system have been subjected to taxation (effectively reducing benefits, particularly since those limits weren’t adjusted for inflation)—and most honest folk (even politicians) will admit that those same kinds of changes will be required again to avert the future funding crisis.

To get a sense for just how endemic Social Security is to retirement planning, just try finding a retirement income needs projection that doesn’t have as a foundational baseline Social Security benefits. Or consider that an emerging strategy to compensate for retirement savings shortfalls is to use those savings to postpone Social Security claiming in order to maximize those benefits. Indeed, considering how many Americans rely on Social Security as their sole—or at least a primary—source of retirement income, you’d think addressing the looming shortfall would be a matter of high priority for policy makers. But for the most part it seems to be left to “someone else, some other time.” 

Without a doubt, Social Security is most certainly the biggest retirement assumption—by individuals, retirement planners and legislators alike. At a time when we’re working to broaden coverage, to expand the impact of automatic plan design features, and the reach of state-run IRA programs, we know that as valuable, even essential, as those steps might be in broadening and deepening the success of the private retirement system—they won’t be “enough” if we don’t shore up the baseline foundation upon which the nation’s retirement security is currently predicated.

The “math” in the trustees’ report suggests we just picked up an “extra” year to solve the problem. Let’s not waste it.

- Nevin E. Adams, JD


[i] Lest we forget, the Medicare program is in (even) worse shape. But that’s a post for another day.

[ii] Not that the potential beneficiaries have a solid grasp on how the program works even under the best of circumstances—see Many Near-Retirees in the Dark About How Social Security Works.

Saturday, June 04, 2022

Middle "Grounds"

A new report entitled “The Missing Middle” by the National Institute on Retirement Security (NIRS) treads some all-too-familiar ground, myopically focusing on one element of the nation’s private retirement system.

The articulated concern is, of course, the “middle”—an income grouping for which Social Security’s progressive structure doesn’t reach high enough to provide an adequate replacement income, but that lacks the more expansive financial wherewithal of those at the upper end of the income strata.

According to the paper, the tax incentives that arguably existed at the birth of the 401(k) have been muted due to lower marginal tax rates and the expansion of the standard deduction—both of which serve to mitigate the tax burden on lower-income individuals—but in the process also arguably lessen the financial incentive for deferring taxes. And if that were not enough, the authors also argue that the “…tax benefits relating to investment returns may be less in a market with lower returns.”

Of course, the focus of the authors here is the tax incentives for retirement savings[i]—and, unsurprisingly, the premise is that those with lower incomes—and thus less tax liability—get less from the current tax deferrals afforded 401(k) contributions than do those at higher incomes (who pay more in taxes). And, if you look only at that aspect—and that’s where most such critiques stop—it’s a fair point.

Before going into the shortcomings in that analysis, I’ll admit that there are certain legitimate economic realities that the paper highlights—that higher-income (and by this we don’t necessarily mean wealthy) individuals are more likely to have access to a retirement plan through work, that there are racial aspects that correlate to wealth inequities and access in the workplace, that the Saver’s Credit as currently designed (requiring a long-form tax filing to claim and being non-refundable) aren’t available to many who would otherwise be eligible, and that Social Security, though an underlying foundation of private requirement as a whole, and particularly for lower-income individuals, has funding issues of its own to fulfill the current benefit promises.[ii]

‘Missing’ Interactions

Unfortunately, as noted above, these types of analyses always gloss over the interrelationships between the tax incentives and the creation of these plans in the first place. It is assumed (generally implicitly) that employers that want to be considered an “employer of choice” will be forced to offer these plans regardless of the tax preferences to do so. Let’s face it, the tax preferences—though modest at an individual level—do provide an incentive to not only offer the plan, but—in most cases—to provide a matching contribution. A matching contribution that these type critiques always seem to gloss over (it does make their math simpler). And let’s face it, there’s no question that having access to a plan matters—even this NIRS paper acknowledges that those with access are 15 times more likely to save. 

What’s also glossed over is the impact of non-discrimination tests and legal contribution limits—limits that work, and work as designed, to keep an effective balance between the benefits of higher-paid and other workers. In fact, data from the Employee Benefit Research Institute has proven that while higher-income individuals do have higher account balances, those balances are in rough proportion to their incomes. 

In calling for a “recalibration” of what they see as a “fundamentally inequitable system,” the well-intentioned authors are missing the mark. By focusing exclusively on the individual tax preferences, while at the same time ignoring the impact of tax preferences on the decision to offer a plan in the first place, as well as the influence of non-discrimination testing in encouraging an employer match (not to mention the financial impact that has on the retirement prospects of non-highly compensated workers), they—and their purported solutions—turn out to be missing the point—and the very “middle” they claim the current system overlooks. 

- Nevin E. Adams, JD


[i] Once again, the trade-off for deciding to defer taking pay now, and depositing it in a trust subject to various restrictions and pre-withdrawal penalties is that you don’t pay taxes on compensation you haven’t gotten access to.

[ii] To address the perceived shortcomings identified, the authors have several solutions. Specifically, they want to boost and expand Social Security, federalize the state-run IRAs, target the Saver’s Credit to participants in those programs, and perhaps introduce a state version of the refundable government credit in place of tax incentives, which would equalize the credit. 

Saturday, May 28, 2022

Vested "Interests"

 The latest academic “dig” against 401(k) plans? Vesting schedules.

More specifically, firms with a combination of high turnover and vesting schedules, which means that workers are leaving behind employer contributions. Or, in the parlance of these new critics, being “robbed.” 

I stumbled across this “scandal” in an op-ed provocatively titled, “This giant pension scandal is hiding in plain sight,” which, in turn, drew from the points made in an academic paper titled, “Megacompany Employee Churn Meets 401(k) Vesting Schedules: A Sabotage on Workers’ Retirement Wealth.” The “scandal” is the legal vesting schedules under ERISA, notably the three-year variety in place at certain large, high-turnover employers.

The MarketWatch article[i]—and, more significantly, the academic paper[ii] upon which it is based, see the vesting schedule as part of some orchestrated conspiracy deliberately crafted to “rob”[iii] individuals of benefits/compensation to which they are entitled—ostensibly because they are incapable, and arguably in some cases, unable, to hold on to a job for a full three years.

Indeed, Amazon draws most of the criticism here—not only for its three-year vesting schedule, but for the emphasis CEO Jeff Bezos has apparently placed on encouraging high turnover as a means of keeping perspectives “fresh.” That might work for Amazon’s business model (I suspect it matters more about the “who” than the “how often”), but in my experience, most employers find turnover to be costly, requiring the expense of finding replacements, training them, and then waiting for them to come up to speed. 

That said, a plan’s vesting schedule wouldn’t exactly seem to be “hidden.”[iv] Indeed, I have long found it to be an element that warrants a reasonable amount of discussion and specific focus during enrollment meetings, and for the very reason it exists: as an incentive to reward/retain/encourage longer-term workers (or at least it did before the shift in emphasis to automatic enrollment). I say longer term because the notion of long-term workers has shifted considerably since ERISA was passed in 1974, when the 10-year cliff vesting that was common among pension plans at the time reigned. Of course, the Tax Reform Act of 1986 established new, shorter minimum thresholds for vesting. Indeed, by the “norms” that were in place when the 401(k) came to prominence, 100% vesting within three years is “lightning fast.” 

So, what’s the beef? The argument put forward is that these vesting schedules create a “bait and switch” of sorts—the promise of an employer match kept just out of reach by a vesting schedule purposefully selected to kick in outside of the average worker’s tenure. And if that seems a tad too Machiavellian, there’s the overt actions that have been taken (particularly during COVID) by employers to reduce the workforce. 

That said, the paper speaks to some issues that are worth considering: the financial vulnerability of lower income workers, not to mention the financial literacy gaps there, and the retirement wealth gaps between men and women, as well as racial wealth gaps. We know these are real, but we also know that they are often remedied with access to a plan at work, assisted by plan design features like automatic enrollment and qualified default investment alternatives like target-date funds. 

Indeed, with regard to the latter, one of the two main recommendations of the paper (albeit with some editorializing) is to is to “collect data so we can truly assess the monster we are dealing with.”

However, the other main recommendation is problematic, if not unnecessary—specifically that we “prohibit megacompanies from using vesting schedules.” That, despite the fact that the paper itself cites data both from Vanguard and the Plan Sponsor Council of America which says that roughly half of the nation’s largest employers already provide immediate 100% vesting. 

Does a vesting schedule provide an incentive to “stick around”? Arguably it does (though it’s probably not going to trump job criteria like location), but in the words of the paper’s author, “…using vesting schedules to reduce turnover only works if employees understand the vesting policies.”

Ultimately, I’d argue that the issue to address isn’t vesting. After all, those who have access to a retirement plan, regardless of vesting, have a real edge on those who don’t. And let’s not kid ourselves—there are plenty of valid reasons, particularly amid today’s so-called “Great Resignation,” to leverage benefit programs to attract and retain talent. 

Certainly, the company match can—and should—be a factor in that arsenal, and I’d argue that the employer has a “vested” interest in that outcome—and that workers, properly informed and educated to appreciate that benefit, do as well. 

- Nevin E. Adams, JD


[i] In a nutshell: Some of America’s biggest companies run their shop floors so that low-paid front-line staff “churn,” or leave within a couple of years. This includes retailers, internet companies, leisure and hospitality companies and others. Some do it deliberately. Others do it by default, by treating such workers as disposable.

[ii] Authored by Samantha Prince, associate professor of law at Penn State Dickinson Law.

[iii] Yes, “robbed” is the word they use: “That employee is robbed of their compensation and that same $100 then goes into the pot to be allocated to other employees. When there is no immediate vesting, the company pays into the plan on one employee’s behalf but then can use that same money on behalf of another employee. This could be said to be akin to robbing Peter to pay Paul. And it is currently permissible. High turnover companies are reducing compensation costs by using the 401(k) vesting schedules.”

Saturday, May 07, 2022

Mothers' Day

As kids, we often struggle with our parents’ attempts to help us make good choices—and, at least in my family, Mom caught the brunt of all that (at least from me). 

We were probably like most families at the time in that we never really talked about money or finance. Doubtless that was in no small part because neither of those were in abundance in our household. But mostly, I suspect, it was because that was just one of “those” topics that were deemed to be private.

In our house Mom was definitely our family’s CFO. See, like many in his generation, my dad wanted to hold the checkbook, but it was Mom who always made sure that there was money in the account. She’s the one who started setting aside money from her paycheck in her 403(b) plan at work—and continued to do so, even when my father was convinced they couldn’t afford it—and made no secret of that opinion. Or did until he got a glimpse of the statement that showed Mom’s retirement account growth—and then, inspired by that example, he began setting money aside for retirement as well. They did so relatively late in life—preachers and teachers don’t have a lot of “extra” income, after all (especially not with four kids)—and yet, with careful planning—and diligent saving—they managed. My mother—now nearly 92—is (still) living on her own and financially independent.  

Of course, women tend to live longer (and thus are likely to have longer retirements to fund), tend to have less saved for retirement (a result of lower incomes, as well as more workforce interruptions, both when children are young, and as their parents age), and in addition to longer retirements, those longer lives mean that they are also more likely to have to fund what can be the catastrophic financial burden of long-term care expenses. Among the unexpected expenses in retirement—as parents all know, are those related to your kids—because, even after they leave home and have kids (and expenses) of their own—they’re still your kids.

Sadly, because we know how much difference it can make in retirement savings, women are also less likely to work for an employer that offers a retirement plan at work—and more likely to be part-time workers, and thus less likely to be eligible to participate in those plans even when they do have access. Oh, and like my mother, they tend to outlive their spouses—often by far more than the variance in average life expectancy tables suggest.

And yet, more than a quarter century “in” to her retirement, Mom’s sacrifices over the years (which continue to this day) have allowed her to have one that is, while certainly not luxurious, comfortable. Oh, like many in her generation, she’s constantly worried about being a “burden” to her family, though—because of her preparations—there’s not much chance of that.

Not surprisingly, Mom was the one who encouraged me to start saving in my workplace retirement plan as soon as I was eligible—and while I wasn’t always smart enough to take Mom’s advice in every situation, I’m happy to say that on this I did. 

Yes, mothers give us a lot, not the least of which is life itself. And on this particular Mother’s Day, I’m thankful that I’m going to be able to thank her… in person. 

- Nevin E. Adams, JD

Saturday, April 30, 2022

"Broken" Premises

 Perhaps because of the recent full moon, the nation’s 401(k) “haters” were out in force.

Yes, last week we were “treated” to a Bloomberg op-ed with ideas on how to “fix” America’s broken retirement savings system, a back-handed compliment (of sorts) on SECURE 2.0 in Forbes from Teresa Ghilarducci, and the trifecta was completed with an academics op-ed in the Washington Post alleging that the current retirement system is “built for the rich.” 

Most of the criticism was focused on the same old myopic view on taxes and tax preferences—all flavored through the prism of a highly biased preference for the involvement of the federal government in such matters, rather than the private sector.


Key Points

So, let me take a couple of minutes to make a few points that always seem to be glossed over:

  1. Tax deferral is not tax avoidance. Those contributions and earnings will be taxed (though generally outside the 10-year budget scoring window Congress uses).
  2. The ability to save for retirement on a pre-tax basis is a powerful incentive—even, and perhaps especially, for those that academics argue have no rational reason to do so (because, on a net basis, they have no federal income tax liability). 
  3. Tax preferences encourage not only plan participation (though it does that), but also the creation/existence of retirement plans—in which lower income workers are 12-15 times more likely to save than on their own. 
  4. Non-discrimination tests and legal contribution limits work (as designed) to keep an effective balance between the benefits of higher-paid and other workers. In fact, actual data proves that while higher-income individuals have higher account balances, those balances are in rough proportion to their incomes. They are not “upside down.” 

Now, with those elements in mind (we’ll return to them throughout), what did the “haters” have to say?

The ‘Fixes’

Well, the Bloomberg editors’ “fix” to the system they claim is “broken” involves: (1) making access universal (but wait, what about Social Security?)—with a 3% auto-default rate with an opt out (they cite the UK’s NEST opt-out rate of 8%, though the opt-out rate for comparable state-run IRA programs in the U.S. is three to five times larger); (2) making it “simple” (the federal government’s Thrift Savings Plan, or TSP was cited), ostensibly with an abbreviated fund menu—or perhaps just because it’s a government solution; (3) making it “portable” (actually, they want it centralized, presumably with the federal government, so that it never has/get to be moved/rolled over), and (4) they want it to be “progressive,” which basically means shifting the current deferral of taxes to a straight-up government match to “the lowest earners.”[i]

There’s really nothing new here—the solution seems to be, more or less, a “nationalization” of retirement savings—with a program focused on helping those at the lower end of the income scale, but completely ignoring the vast sea of middle-income savers—for whom Social Security alone likely won’t come close to replicating their retirement income needs. 

The Washington Post op-ed was crafted by Daniel Hemel, a professor at the University of Chicago Law School and a visiting professor at New York University School of Law. He seems quite angered at the bipartisan support for SECURE 2.0 (actually the Securing a Strong Retirement Act of 2022) as some kind of sell-out by Congress to the financial services industry. He has an issue with “mega-IRAs,” but he also takes aim at Roth contributions, the extension of the required minimum distribution timeline, the non-tax refundability of the Saver’s Credit, as well as the scaled increase in the catch-up limits—all of which are characterized as either a giveaway to the rich, a budgetary “gimmick”—or both. He offers no solutions to any of this—though he does suggest that a focus on a strengthened Social Security would be a better use of their time (I, for one, would support that). Nor is there an acknowledgement that somewhere along the way this system “built for the rich” has somehow managed to wind up with roughly two-thirds of its participants in tax brackets that by most measures would fall significantly lower than that label would encompass. Groups for which this “broken” system is a lifeline beyond the baseline of Social Security and the pension benefits they never had. 

And then, just ahead of that article, Teresa Ghilarducci, a familiar critic of 401(k)s, pens an article ostensibly focused on the provisions of SECURE 2.0 (even taking the time to try and explain why it garnered such strong bipartisan support) on her way to pointing out why her proposal (now labeled the Ghilarducci/Hassett/EIG retirement proposal) is superior. Now, most of us would think that legislation—any legislation—that passed the U.S. House of Representatives by a margin of 414-5 would have to be on something as innocuous as naming a post pffice—that it would advance so many aspects of retirement security instead is a testament to the importance of the issue(s), and the potential to make strides in addressing them. 

Well, Ms. Ghilarducci seems to think that while SECURE 2.0 is perhaps better than a poke in the eye with a sharp stick (my words, not hers), but she claims the fixes it provides are too little (and probably too late), compared with her solution (if bipartisanship in the U.S. Congress is quickly dispensed with, she takes great pride in her alignment with conservative economist Dr. Hassett) that would build a TSP-like program for—well, everybody—or at least those who don’t already have a retirement savings plan at work. This particular article doesn’t go into the details of her solution, but we’ve seen (and written) about it before. Mind you, she’s not really worried about what you and I might consider middle-income workers—her focus is on the lower end (less than $52,000 median household earnings). It calls for a government (rather than an employer) match—but one that is only 3%. Now, that’s a number that has appeared in previous proposals she has put forth—and Jack VanDerhei, while at the Employee Benefit Research Institute, projected that it comes in well under where the status quo brings that same group in the current system.[ii]

‘Broken’ Premises

Now, those of us who actually work with real people know that this so-called “broken” system works amazingly well—for those who have access to it—including, most especially, those at the lower end of the income scale. The academics routinely target the well-off in their criticisms, but ignore the needs of middle-income households for whom Social Security will almost certainly not be… enough. And completely discount/ignore the role that the current tax preferences play in fostering the formation and maintenance of these retirement plans. 

Indeed, underneath all of the criticisms, the real issue seems to be that—as we’ve noted repeatedly—not enough working Americans have access to that system. What these critics don’t seem to appreciate is that, rather than closing that gap by encouraging more plan formation and participation, these random op-eds—often based on myopic views and faulty premises—only serve to undermine that goal. But then, perhaps there’s a reason… 

There are plenty of success stories out there—I’ll bet every single one of our 35,000+ readers know one, ten, a dozen, perhaps hundreds… it’s past time we started telling them.

- Nevin E. Adams, JD


[i] Weirdly, as a throw-in they suggest that folks should be able to “tap their accounts for the occasional emergency expense”—which they claim would “save billions more that would otherwise go toward interest on often-predatory payday loans.”

[ii] My thinking is that, like earlier proposals, her math works because she assumes that any balances not actually withdrawn by the individual (and perhaps their spouse) would be absorbed into the “pool” and used to fund other payouts.

Saturday, April 23, 2022

Planes, Trains, and ...U-Hauls?

One of my favorite holiday movies is “Planes, Trains, & Automobiles”—but who thought so many would have to live it? 

The movie I’m referring to is that 1987 John Hughes classic starring Steve Martin and John Candy as a pair of travelers (Martin an advertising exec, Candy a traveling shower curtain ring salesman—and you think you have a hard job) trying to get home for Thanksgiving. There are any number of misadventures along the way—involving the aforementioned means of transportation on the trip from New York to Chicago… via Wichita and St. Louis. 

Well, a couple of weeks back several hundred advisors found themselves reliving that experience as a series of unrelated events emerged to thwart their scheduled travel to the NAPA 401(k) Summit in Tampa. It started early the day before the event with a strike by Alaska Airlines pilots, by mid-morning Southwest Airlines was experiencing ““intermittent performance issues following routine overnight maintenance of some of [its] backend technology,” there was snow in the upper Midwest, and in early afternoon the southeast found itself covered by a massive series of thunderstorms—all of which had an impact—and a ripple impact across the systems of travel—and all at a time when air traffic was arguably even more complicated by a large volume of Spring Break traffic as well. And that’s not even considering the normal issues with mechanical issues that some who missed the other events had to contend with.

As you might imagine, a good part of that Saturday was consumed not only worrying about, but hearing from, and responding to, speakers and staff who were ensnarled in those travel issues. At the same time, I heard from at least a dozen individuals who, on the ground in Tampa, but aware of the travel issues, reached out to me to volunteer their services as a stand-in for speakers who couldn’t get here in time. Meanwhile, there was the “call” to be made with regard to the outdoor activities that were being planned for Sunday (Flo-Rida) and Monday nights.

Sunday morning dawned with a great deal of uncertainty as to what we’d be looking at in terms of attendance and speakers. But what impressed me throughout was just how hard people were working to get to Tampa. And over the three days of the conference people just… kept on coming… 

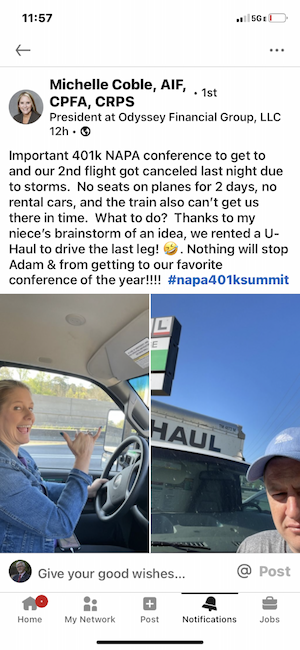
There were some amazing stories of persistence and perseverance throughout—but the one that made the deepest impression on me was that of Odyssey Financial Group’s Michelle Coble and Adam Bahner. Based in Oklahoma City, OK, they got as far as Atlanta when not one, but two of the flights from there to Tampa were cancelled—and they were told that there were no seats on the flights out to Tampa for two days. There were no rental cars to be had, and the trains—well, they wouldn’t get to Tampa on time. So they rented a U-Haul—and drove that last leg from Atlanta to Tampa! 

When all was said and done, we had an amazing conference. Sure, some couldn’t get there—many despite enormous effort and inconvenience. But it was clear from the opening session all they way through to the close that those who were there were there because they really wanted to be there—and the level of enthusiasm and engagement—and I think the quality of the content and networking—were through the roof[i].

So, my sincere thanks and appreciation to the speakers and sponsors, to those who “stepped up” to fill gaps, and those who volunteered to do so (because even if we didn’t have to call on you, it relieved some planning pressure)—to the steering committee who helped ensure those gaps were filled, to the conference staff for all the extra work (and stress) that accompanied all this uncertainty.

But most especially, my thanks to all who (including those above) made those (extraordinary) efforts to “get there” via planes, trains, automobiles—and even U-Hauls—to be part of what, by any measure, was an extraordinary event! 

p.s.: Mark your calendars now for the NEXT one—April 2-4, 2023 in San Diego!


[i][i] And, despite all the bad weather on Saturday, the weather during the conference was great, and the outdoor events unaffected!

Saturday, April 16, 2022

Not-So-Unforeseen Outcomes

 Thanks to their mother, my kids have grown up with a variety of pets in our house—but none more bizarre than our experience with… a chicken.

My son’s elementary school class had been exposed to the miracle of life over the course of several weeks by watching a set of chicks spring forth from eggs that had been carefully tended by the class. Once hatched and ready to be turned loose, the teacher offered to let selected children take one home—provided they obtained their parent’s permission, of course. My son was smart enough to ask his mother—who, seeing how much it meant to him—and much to my amazement, acquiesced to the request. 

And so “Grr”[i] entered our lives. Mind you, we were living in a residential neighborhood in Connecticut at the time, miles and miles from anything remotely resembling a farm. That said, the little peeping chick was adorable, and my wife persuaded me that, as the chick grew we’d be able to erect a small pen in the back yard. We even joked about being able to have fresh eggs.

Or did until the day we discovered that Grr was biologically incapable of such things—at which point it was clear that while we had thought things might turn out one way—well, we now had a loud, smelly and fairly aggressive bird in our house! It’s not that this was completely unforeseen, but it certainly didn’t take a lot of imagination to see that it could go “wrong.”

In that spirit, there are a couple of initiatives rumbling around in Congress at the moment—arguably well-intentioned, but almost certainly likely to have consequences that are not unforeseeable, though surely not what their champions expect or intend. 

The first of these is an initiative focused on expanding spousal consent—not the beneficiary designation requirement in place since the mid-1980s, but one that would basically require an in-person notarized consent for most distributions. The second revolves around discussions to significantly expand the size and flexibility of emergency savings accounts. 


‘Missed’ Directions

The expanded spousal consent provision is well-intentioned, of course. Much as the beneficiary designation requirement, it is designed to prevent one spouse from taking advantage of the other by wiping out what might well be their life savings without their knowledge or involvement. On the other hand, it doesn’t require much imagination to, in a day when men and women are about equally likely to have a 401(k), envision a situation where an abused spouse, needing to access the funds in their account to escape their situation, would be precluded by this legislation from doing so by the very spouse they are seeking to escape.[ii]

Now as for those emergency savings accounts—while the notion is quite popular these days—the problem lies with an idea being touted by the Aspen Institute. It would establish a sidecar emergency savings account with your 401(k) that could be matched—but that you could basically withdraw for pretty much any reason once you got the match. More on that in a minute.

Now, emergencies come in all shapes and sizes—but the Aspen proposal is calling for $5,000 in those accounts (rather than the $1,000 embodied in legislation such as The Enhancing Emergency and Retirement Savings Act of 2021—and they’re suggesting it as $5,000 every year. Five thousand dollars that could be put in the “emergency” savings account every year (just) long enough to get the match—and then, as mentioned above—withdrawn for pretty much any reason whatsoever. And then the next year they could do it all over again. And again. In fact, it doesn’t require a lot of imagination to see this turning into one of those “Christmas Club” savings accounts that banks offered once upon a time. Which arguably stands to create a whole other type of emergency: retirement plan “leakage”—on steroids.

You don’t need 20/20 hindsight to know that bringing a chick into a suburban Connecticut home won’t end well. We did it with a genuine desire to do something nice for our son—and hoped in our hearts that it would turn out differently than our brains would acknowledge. It didn’t, of course—but it turned out to be a situation that didn’t last long, and—thanks to a farm-owning colleague—had a (relatively) happy ending.

Something that ill conceived legislation, however well intentioned—can’t—and shouldn’t—depend upon. Particularly when the potential negative outcomes are… not so unforeseen.

- Nevin E. Adams, JD


[i] While the name eventually seemed to fit his personality, my son simply chose to name it after a favorite character in the “Invader Zim” cartoon series.

[ii] The good news is that the champions of this legislation have decided to study the matter and its potential implications under the auspices of the Government Accountability Office.

Saturday, April 02, 2022

A Thumb on the Scale(s)?

Years back I remember being part of a Q&A with a group of plan sponsors—the focus was the challenge of not only getting, but keeping their plans in compliance, while also looking for creative ways to engage and encourage participants. Then at one point, a tired looking gentleman, expressing frustration with the pressures of audits and litigation, said: “I wish the DOL would just tell us what to do.” 

I cautioned him at the time that he ought to be careful what he wished for—that he might just get it.

Sure enough, in mid-March the Labor Department issued a “compliance assistance release” which was unique both in format and, arguably, focus. It reminded plan fiduciaries of the significance of their review and assessment of prudence of plan investments—and then said in no uncertain terms that it had concerns about the ability of cryptocurrency to meet those high standards. Indeed, the release plainly stated that those who did include such options could “expect to be questioned about how they can square their actions with their duties of prudence and loyalty…”—not just as standalone options on the menu, but even through a brokerage account. And so, while not an outright prohibition, it seems fair to say that it’s likely to have what lawyers call a “chilling effect” on cryptocurrency as a 401(k) investment option.

In late December the Labor Department issued a statement on the use of private equity in participant-directed plans—stating that, except in a minority of situations, plan-level fiduciaries of small, individual account plans are not likely suited to evaluate the use of PE investments in designated investment alternatives (DIAs) in individual account plans. It represented a step back from a June 2020 information letter that affirmed that PE investments “as a component of a professionally managed multi-asset class vehicle structured as a target date, target risk or balanced fund” can be offered as an investment option for participants in defined contribution plans under ERISA. It seems likely that some private equity firms (or those promoting such investments) had taken the initial guidance as something of a green light to promote those options beyond the limitations of the original letter—leading the Labor Department to clarify its position—and, arguably, to shut down active consideration of those options, at least by “small, individual account plans.” 

And then, of course, there’s the focus on ESG options, which the Trump administration clearly tried to undermine with its proposed and then (slightly muted) final regulation—and which the Biden administration first announced that it would not enforce, and has since then, with its own proposed regulation, sought to swing the pendulum in favor of those options—arguably to the point of not only encouraging, but requiring, consideration of those factors.

The reality is, of course, that times change. And even if the long-standing precepts of prudence and fiduciary responsibility haven’t changed, the environment in which those determinations are made has. Cryptocurrency wasn’t a “thing” until fairly recently (and it didn’t take long to find its way into 401(k) platforms), and those who may have misapplied (accidentally or “on purpose”) the Labor Department’s statement on private equity needed to be reminded. ESG is certainly a relatively recent—though not brand new—focus—but plan fiduciaries can perhaps be forgiven for feeling a bit “whipsawed” by the shifting sentiments between administrations.

Generally well-intentioned, the perspective of even the most seasoned and expert regulatory professional sometimes fails to appreciate the impact in the “real” world. That’s the value in the access—and influence—that NAPA, armed with the input, insight and perspective of NAPA members, provides to these processes. Insight and influence that allows you to “put a thumb on the scale” in providing a practical and pragmatic perspective on the rules and regulations that guide our industry— now, and in the days ahead. 

- Nevin E. Adams, JD

p.s.: Speaking of which, this would be a great time to get involved via the NAPA DC Fly-In Forum. Check it out—and apply today—at https://napadcflyin.org.